
July brought two reminders that somebody, somewhere, is setting a floor under farm prices. On July 4, 2025 the President signed the budget reconciliation law, Public Law 119-21, and buried in its pages is a new set of reference prices for commodity crops. Corn moved from $3.70 to $4.10 a bushel, soybeans from $8.40 to $10.00, wheat from $5.50 to $6.35, as the farmdoc daily team at the University of Illinois laid out on July 15. And since February, USDA's Economic Research Service has been forecasting net farm income of $180.1 billion for 2025, up 26.4 percent, with most of that rise coming from direct government payments that jump from $9.6 billion to $42.4 billion.
Neither number lands on a farm that sells by the bunch, the dozen or the quarter beef. There is no reference price for salad mix. Nobody in Washington sets a floor under pastured pork. For a market farm or a grass-based herd, the floor is the cost of production, and most small farms could not tell you what theirs is to the dollar.
This article is about finding that number and letting it set your prices, instead of the other way around.
Start with one enterprise, not the whole farm
An enterprise is a single product that leaves the farm with a price on it: a crop, a class of livestock, a line of eggs. Penn State Extension describes an enterprise budget as an estimate of the receipts, costs and profit from producing one of those products, built on a unit that fits it: an acre for field crops, square feet for a greenhouse or tunnel, a head or an animal unit for livestock.
For a diversified farm, choosing the unit is half the work. A 100-foot bed is a sensible unit for a market garden because that is how you plant, weed and harvest. A cow and her calf is the unit on pasture. A flock of 200 hens is the unit for eggs. Keep the units steady from year to year so the budgets can be compared.
The reason to work enterprise by enterprise is that averages hide things. Whole-farm books can show a profit while two enterprises carry three others that lose money every week. We wrote about whether regenerative farming can be profitable years ago; the honest answer was always "which enterprise, on which farm, at what price." Our belief in always simplifying starts here: one product, one sheet of paper, one unit.
The easy half: variable costs
Variable costs rise and fall with how much you produce. Penn State's list for crops is the one to copy: seed or transplants, fertilizer and lime, pest control, fuel, machinery repairs, crop insurance, hourly or seasonal labor, marketing, and interest on operating capital. For livestock it is feed, herd health, breeding, labor, marketing and operating interest. Rented land or buildings belong here too.
Nate Bruce at the University of Delaware adds a step many cash operators skip: charge operating interest on your variable expenses whether or not you borrow, because the money tied up in a crop is money that could have earned a return somewhere else. He calls it the opportunity cost of short-term capital, and it belongs on the budget.
Most farms can pull these numbers from receipts in an afternoon. The pieces they miss are the per-unit ones: the clamshell, the rubber band, the egg carton, the booth fee divided by the units you actually sold that day. Write them on the budget as a cost per unit, not as a lump at the end of the year.
The half people skip: fixed costs and overhead
Fixed costs do not move with output. Penn State lists depreciation, taxes, interest on investment, land, repairs on fixed assets like buildings and fencing, and insurance. One detail matters for the small farm: use straight-line depreciation over the years you will actually use the asset, not the accelerated schedule you may elect on Schedule F. The tax return is built to lower this year's bill; the budget is built to tell the truth about next year.
Then there is general farm overhead, the spending that belongs to no single enterprise. ERS's cost and returns accounts put farm supplies, marketing containers, hand tools, power equipment, building maintenance, utilities and general business expenses under that heading, and they allocate it to each commodity by its share of the farm's operating margin: a commodity that produces 30 percent of the margin carries 30 percent of the overhead, taxes and insurance.
On a small farm a simpler rule works, as long as it is applied the same way every year: allocate overhead by share of gross sales, or by share of labor hours. Pick one, write it on the budget, and do not change it to make a weak enterprise look better.
How much does the fixed half matter? Texas A&M's 2025 cow-calf budget for Central Texas, 40 cows on native pasture, puts variable costs at $668.79 per animal unit and fixed costs at $495.20, for a total of $1,163.99. Pasture alone is $350 of the fixed half. Leave it out and the herd looks a third cheaper than it is.
Put a wage on your own hours
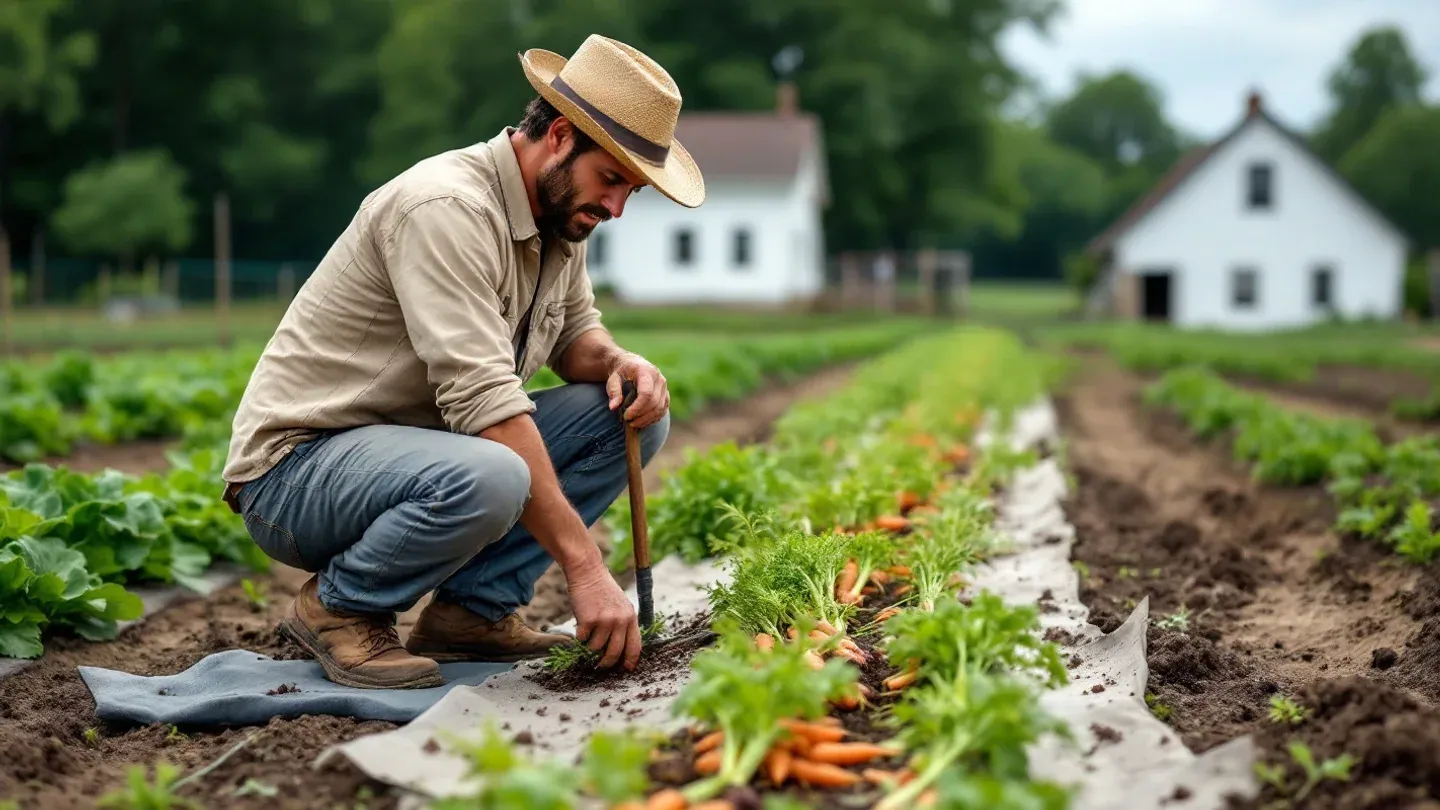
Unpaid labor is the largest hole in most small farm budgets. ERS values an operator's unpaid hours at the wage that operator could earn off the farm, and that is the right idea: your time has a price whether or not you write a check for it.
If you want a floor, use the hired rate. USDA's May 2025 Farm Labor report found that farm operators paid hired workers an average of $19.52 an hour in the April reference week, with field and livestock workers combined at $18.43. If an enterprise cannot pay you that for your hours, it is paying you less than you would pay a hired hand to do the same work. That is the same standard we hold ourselves to with interns and apprentices.
To price the hours, you have to know them. Three weeks with a notebook in the truck, by enterprise and by task, will tell you more than a season of guessing: seeding, transplanting, weeding, harvest, wash and pack, market day, deliveries, bookkeeping. On a market farm the hours after harvest, washing and packing and selling, often outrun the hours spent growing. On pasture the surprise is usually fence moves and water.
Break-even per unit
Now the arithmetic. Penn State and Delaware give the same two formulas. Break-even price is total costs divided by expected yield. Break-even yield is total costs divided by expected price.
Delaware's wheat example shows how hard yield swings the answer. With total costs of $507.36 an acre, the break-even price is $5.97 a bushel at an expected 85 bushels, $4.83 in an excellent year at 105 bushels, and $7.81 in a poor year at 65. Same costs, three very different prices. Run your budget at three yields, not one.
There are also two break-evens, not one. The first covers variable costs only; the second covers everything. In the Texas budget a calf has to bring $137.20 per hundredweight to cover variable costs and $263.77 to cover total costs. Penn State's rule for the gap between them is worth memorizing: in the short run you keep producing if the price clears variable costs and the squeeze is temporary; in the long run the price has to clear total costs, or the day comes when you cannot replace the tractor.
For a market garden the units are smaller but the method is identical. Say a 100-foot bed of salad mix costs you $60 in seed, compost, drip tape and bags, nine hours of labor at the $19.52 hired rate, which is about $176, and carries $40 of overhead and depreciation under your allocation rule, roughly $276 in all. At 40 pounds a bed the break-even is about $6.90 a pound. At 30 pounds it is $9.20. Those are made-up round numbers to show the shape of it; your notebook replaces them.
From break-even to a price list
Break-even is not a price. It is the lowest number on the page. A price adds a margin for the things a budget cannot schedule: a dry August, a well pump, a vet bill, the season you spend building soil instead of harvesting it. Penn State's long-run rule says the enterprise must earn above total costs; a price list that only matches break-even is a plan to stand still.
Then check the number against the market, not against the neighbor's chalkboard. USDA's Agricultural Marketing Service publishes Local and Regional Food Market News: farmers market and produce auction reports for a list of states, and quarterly national direct-to-consumer reports on grass-fed beef, pasture-raised pork and pasture-raised poultry. Those reports tell you where the market sits. Your budget tells you whether you can afford to sit there.
If the going price is below your total-cost break-even, you have four honest moves. Cut a cost you control. Raise the yield per unit, which is where good soil earns its keep. Change the product or the unit: beef sold by the half, quarter and bundle prices differently from the same animal sold by the cut. A dozen eggs carries feed costs that a flock budget makes visible. Or drop the enterprise and put the hours into one that pays. What you do not do is price under cost and plan to make it up on volume.
Once the numbers are in, the price list follows from them. Write it once, in the winter planning weeks, and hold it through the season. Being consistent at the stall is easier when the price is anchored to a budget instead of to a mood, and customers notice. Our guide to a market stall that sells covers the display; this article covers what is on the tag.
Tools that will do the arithmetic for you
You do not have to build the spreadsheet from scratch. Penn State's Agricultural Alternatives series includes sample budgets with a "Your Estimate" column meant to be overwritten. Delaware publishes field crop and vegetable crop budgets, including the 2024 seedless watermelon budget in the fact sheet linked above. The University of Georgia keeps a library of vegetable, row crop and cow-calf budgets, with cost estimates current as of December 2024, and says plainly that they are a guide for entering your own numbers, not a substitute for them. Texas A&M publishes cow-calf budgets by extension district.
If you want to see what real farms actually spent rather than what a budget assumed, FINBIN at the University of Minnesota describes itself as one of the largest and most accessible sources of farm financial and production benchmarks, built from the records of farms in farm business management programs. Its reports let you compare your cost per unit with a group of farms like yours.
For the planning around the budget, SARE's Building a Sustainable Business remains the standard guide, with blank worksheets that walk a farm family from goals to a lender-ready plan. It pairs well with our older piece on farm business plans. Our directory of organizations lists the extension and farmer networks that run budgeting workshops. Our books, films and magazines page carries the farm business titles we keep recommending.
Where the July news actually fits
Back to the reconciliation law. Besides the reference prices, it raised the Agriculture Risk Coverage guarantee from 86 to 90 percent of benchmark revenue, and for the 2025 crop it lets enrolled farms take the higher of the Price Loss Coverage or county ARC payment regardless of the choice they made in the spring. The Farm Service Agency's ARC and PLC page explains the two programs in plain terms: ARC pays when revenue falls below a guarantee, PLC pays when the price falls below an effective reference price.
For a direct-market farm, this is context rather than a plan. Those programs cover base acres of covered commodities. A farm growing forty vegetable crops on six acres, or finishing cattle on grass for a freezer trade, is not in that room. We explained the shape of all this in our farm bill primer. The federal policy that covers all the commodities on a farm under one contract, Whole-Farm Revenue Protection, is written with local and direct markets in mind and insures your own revenue rather than one crop's yield, which is one more reason to know your numbers.
The income forecast deserves the same reading. ERS updates it three times a year, in early February, late August or early September, and late November or early December; the February figure is the one on the table in July and the next revision comes at the end of summer. Whatever the headline says, remember that the February increase was mostly payments, not sales. The line to watch for a farm like yours is cash receipts, and the only cash receipts that matter are your own. Our belief in thinking long term means building a price that survives the years when the headline is bad.
This week
Here is the practical close.
- Pick the one enterprise you suspect is weakest and give it a unit: a bed, a pair, a flock.
- List its variable costs from last year's receipts, down to the rubber band and the booth fee per unit.
- List its fixed costs with straight-line depreciation, and allocate overhead with one rule you write on the page.
- Put a wage on your own hours, no less than the $19.52 hired rate, and start the three-week notebook to find out how many hours there are.
- Compute break-even over variable costs and over total costs, at three yields.
- Compare the result with the AMS local food reports for your region and decide: raise the price, cut the cost, change the unit, or let the enterprise go.
Then do the next enterprise. By the time ERS revises its forecast at the end of summer, you will have a price list that is yours, with a floor under it that nobody in Washington had to vote on.